Credit Card Debt Can Feel Like a Life Problem, Not Just a Money Problem
Credit card debt has a way of becoming something much bigger than a number on a statement. It can follow you into the grocery store, sit beside you while you work, and show up in your thoughts when you are supposed to be sleeping. You may be functioning, paying bills, going to work, taking care of everyone else, and still quietly wondering why your money never seems to be enough.
That feeling is more common than people admit. You swipe because something needs to be paid. You tell yourself you will catch up next month. Then another expense appears. The balance moves slightly—or sometimes not at all—and suddenly months have passed.
And here is the uncomfortable part: the problem is not always that you are irresponsible with money.
Sometimes you are simply exhausted.
Modern life has normalized a level of financial and emotional overload that would have seemed impossible a generation ago. Housing, groceries, insurance, transportation, subscriptions, childcare, unexpected repairs, and everyday necessities can compete for the same paycheck. When your mental bandwidth is already gone, making perfect financial decisions becomes much harder.
That is how the credit card trap becomes so powerful. It does not always begin with one enormous mistake. Often, it begins with dozens of small moments when you are functioning but not okay.
Why Credit Card Debt Keeps You Stuck Even When You Are Trying
The first thing to understand is simple: credit card debt is designed to be repaid over time, and interest can make that time expensive. A balance can remain surprisingly stubborn even when you are making regular payments every month.
Think about what happens when you make a payment and then use the card again for groceries, gas, or an unexpected bill. Emotionally, it feels like you are making progress because money left your bank account. But financially, your balance may barely change.
This creates a frustrating loop:
You spend because you need something.
You receive the credit card statement.
You make the minimum payment or another manageable amount.
Interest is added to the balance.
Another unexpected expense arrives.
You use the card again.
You feel like you are starting over.
After enough repetitions, the debt begins to feel permanent.
That emotional reaction matters. When people believe a problem is impossible to solve, they often stop looking closely at it. Statements go unopened. Balances become something you check only when absolutely necessary. Financial decisions move onto autopilot.
That is not laziness. It is often mental fatigue.
A simple tool such as a Rocket Money budgeting and subscription tracker can help you see recurring expenses that disappear from your account almost invisibly. The point is not to obsess over every dollar. It is to make the invisible visible again.
The Minimum Payment Illusion
One of the most dangerous features of revolving credit is also one of the easiest to underestimate: the minimum payment can make a large balance feel manageable today while extending the problem far into the future.
There is a psychological comfort in seeing a payment that fits inside your monthly budget. But affordability today is not the same thing as affordability over time.
In other words, a payment can be small enough to survive while the total cost of the debt remains large enough to keep you financially stuck.
This is why looking only at the minimum payment can create a false sense of security. Instead, pay attention to the balance, interest rate, new purchases, and how much of your payment is actually reducing what you owe.
The Hidden Emotional Cost of Carrying a Balance
Money stress rarely stays neatly inside your bank account. It can spill into sleep, relationships, work, confidence, and even the way you see yourself.
You might lie awake calculating what needs to be paid next. You might avoid opening your banking app because you already know the number will make you anxious. You might feel guilty after buying something small, even when you genuinely needed it.
Then comes the strange contradiction: you are technically keeping everything moving, but internally you feel like you are falling behind.
This is what financial burnout can look like.
You are answering emails. Showing up at work. Making dinner. Paying bills. Caring for your family. Smiling when somebody asks how you are doing.
But underneath all of that, your brain is constantly running financial calculations.
How much is left?
What if the car breaks down?
What if the rent goes up?
What if I cannot pay the card this month?
That constant background noise creates mental fatigue. And mental fatigue changes behavior. When your brain is overwhelmed, convenience becomes more attractive, immediate relief feels more valuable, and long-term planning becomes harder.
That is why financial change cannot always begin with a stricter budget.
Sometimes it begins with clarity.
When Spending Becomes Emotional Relief
Not every purchase is emotional spending. But sometimes buying something creates a tiny moment of relief in an otherwise exhausting day.
You had a terrible week, so you order dinner. You are overwhelmed, so you buy something that makes your home feel better. You are exhausted, so convenience wins. You deserve a break, so you swipe.
None of those moments makes you a bad person.
The danger appears when the purchase provides temporary emotional relief but creates financial stress that lasts for weeks.
A product such as a Rocketbook reusable notebook can be useful for a different kind of reset: getting the thoughts out of your head and onto paper. Journaling does not magically eliminate debt, but writing down what you owe, what worries you, and what you can control can reduce the mental chaos that often surrounds money decisions.
The Credit Card Trap Is Often Built One Small Decision at a Time
Here is the truth that can feel surprisingly freeing: you do not necessarily need to completely transform your life to start changing your finances.
You need to interrupt the pattern.
Most people imagine financial recovery as one dramatic event. They expect a huge raise, a massive side hustle, an unexpected windfall, or an extreme no-spending challenge to save them.
But sustainable progress is usually quieter.
You stop using one card for everyday purchases.
You cancel a subscription you barely use.
You redirect one automatic payment toward a balance.
You cook at home a few more times each month.
You create a small buffer before throwing every available dollar at debt.
You finally look at the numbers without judging yourself.
Those actions may look insignificant individually. Together, they change the direction of your finances.
Start With the Number You Have Been Avoiding
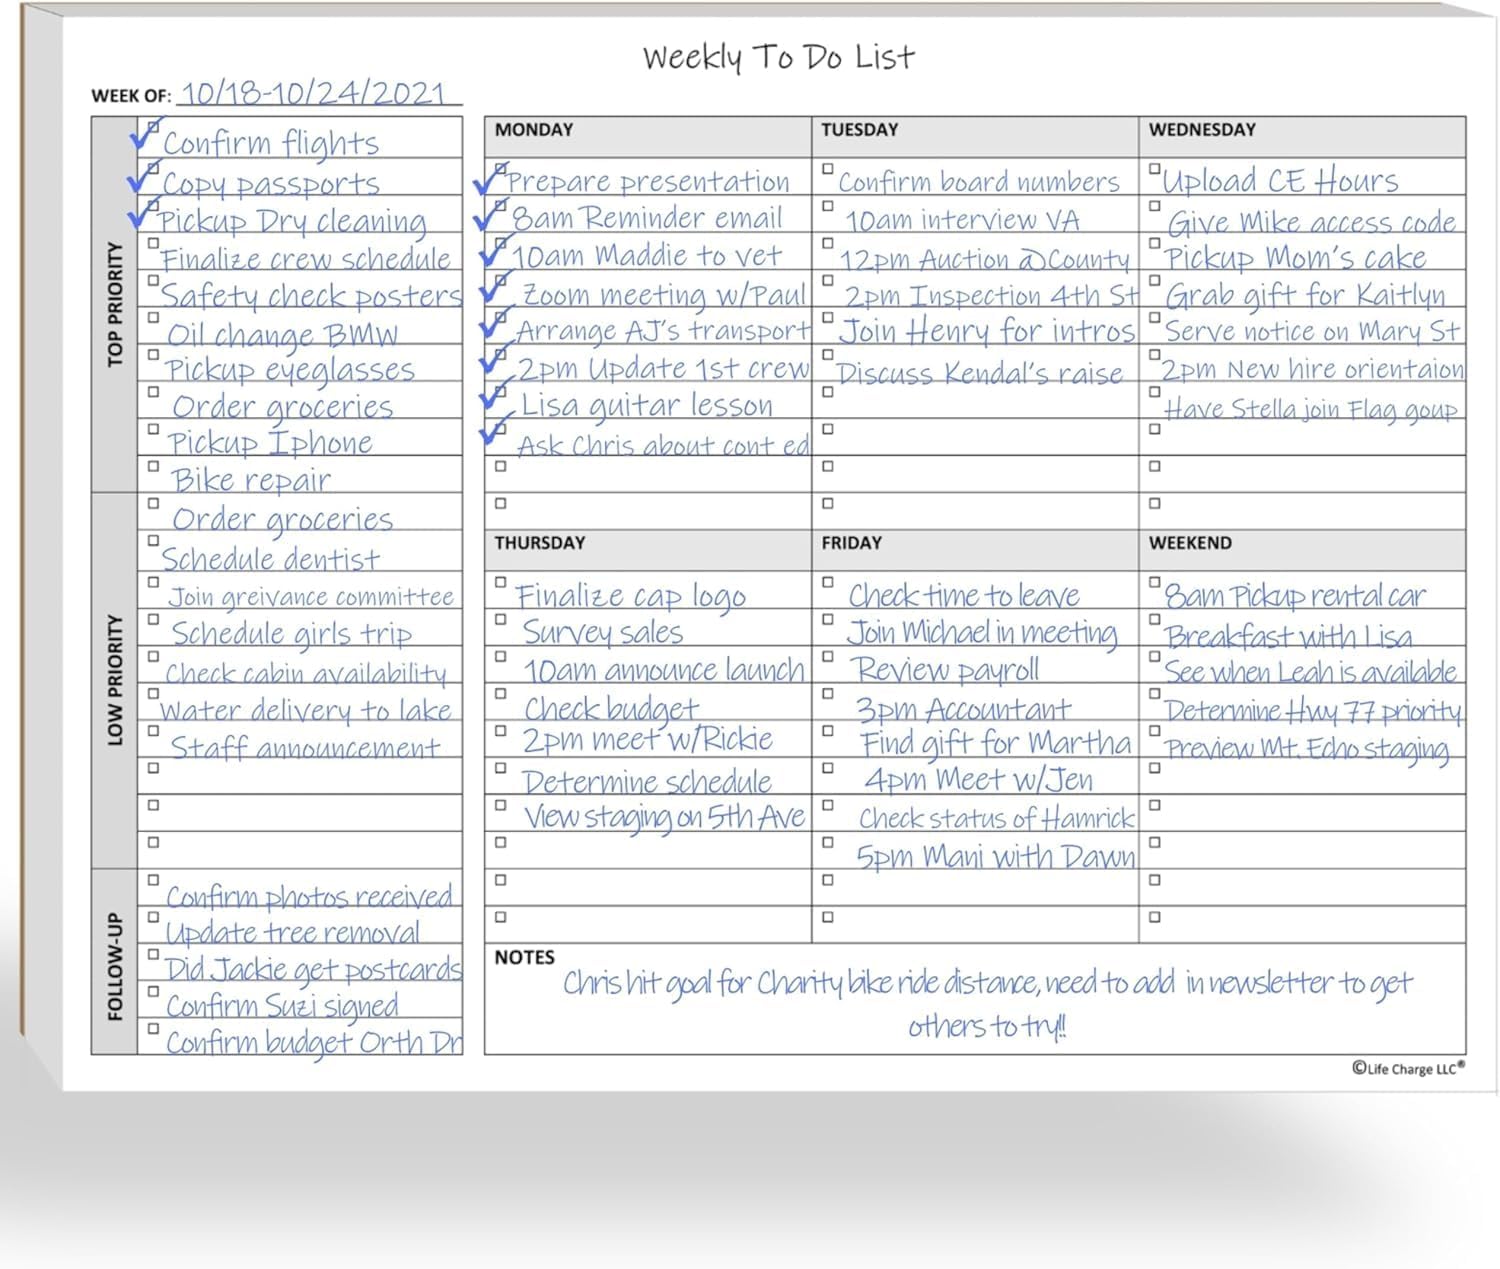
Write down every credit card balance.
Next to each balance, write the interest rate, minimum payment, and due date. Do not estimate. Do not round. Look at the actual statements.
Then calculate your total.
This can be uncomfortable. You may feel your stomach drop when you see the number in one place.
Do it anyway.
Because uncertainty is often more stressful than information.
Once you know the total, you can make decisions based on reality rather than fear.
If organization is the problem, a simple financial planning tool such as a YNAB budgeting system can help you assign your available money intentionally instead of wondering where it went at the end of the month.
How to Break the Cycle Without Making Your Life Miserable
There is a common mistake people make when they finally decide to get serious about debt: they create a budget so restrictive that they cannot maintain it.
They remove every restaurant meal, every small pleasure, every convenience, and every activity that makes life enjoyable. For a few weeks, they feel incredibly disciplined.
Then real life happens.
They get tired. Something unexpected comes up. They overspend. The plan collapses. Shame follows.
A better approach is to create a system you can live with.
1. Stop Making the Problem Bigger
Before worrying about the perfect repayment strategy, identify the expenses that are actively increasing your balance. If possible, stop using the credit card for purchases you could cover with available cash.
This does not mean pretending emergencies do not exist. It means creating a clear distinction between necessary spending and spending that simply delays the discomfort of saying no.
2. Choose a Repayment Strategy
Two common approaches are the debt avalanche and debt snowball.
The avalanche method focuses on paying extra toward the balance with the highest interest rate first, which can reduce interest costs over time. The snowball method focuses on paying off the smallest balance first, creating quick psychological wins that can build momentum.
Neither strategy is about being morally better. The best approach is the one you can actually follow consistently.
3. Protect a Small Emergency Buffer
If every unexpected expense goes directly onto a credit card, debt repayment can become an endless loop. Even a modest cash buffer can help absorb smaller surprises without immediately reaching for plastic.
The goal is not to build a perfect emergency fund overnight. The goal is to create breathing room.
4. Make Your Environment Work for You
Financial discipline becomes harder when temptation is always one tap away. Removing saved cards from shopping websites, turning off promotional notifications, unsubscribing from retail emails, and deleting shopping apps can create valuable friction.
That tiny pause matters.
When you are tired, you do not need more motivation. You need fewer opportunities to make an impulse decision before you have time to think.
What If You Are Already Completely Overwhelmed?
Then start smaller.
Seriously.
You do not have to solve your entire financial life this weekend.
If opening every statement feels impossible, open one. If listing every expense feels overwhelming, track today's spending. If calculating every balance makes you panic, start with the largest card.
One clear action is better than another week of avoidance.
And if money worries are affecting your ability to sleep, give yourself a short financial shutdown routine at night. Write down what needs attention tomorrow, close the banking apps, and allow your brain to stop solving problems for a few hours.
Something as simple as a Hatch Restore sleep routine device may complement a consistent wind-down routine for people who are trying to separate nighttime rest from financial problem-solving. It is not a financial solution, of course. But better rest can make it easier to think clearly and make deliberate decisions the next day.
The Reset Starts When You Stop Calling Yourself the Problem
There is a difference between taking responsibility and carrying shame.
Responsibility says, I need to change what I am doing.
Shame says, Something is wrong with me.
The first can create movement. The second often creates avoidance.
If you have accumulated credit card debt, you do not need to spend the rest of your life punishing yourself for it. You need an honest picture, a realistic strategy, and enough patience to let the strategy work.
Maybe your financial situation is not where you want it to be.
That does not mean it has to stay there.
And perhaps the most important shift is realizing that your goal is not simply to become debt-free. Your goal is to create a financial life that does not require constant emotional survival.
What Financial Freedom Actually Feels Like
People often imagine financial freedom as luxury cars, expensive vacations, or a huge investment portfolio.
But for someone who has spent years worrying about credit card debt, financial freedom can feel much quieter.
It can mean opening your bank account without fear.
It can mean paying an unexpected bill without immediately reaching for a card.
It can mean sleeping without mentally calculating tomorrow's expenses.
It can mean buying something you genuinely need without feeling guilty for three days afterward.
It can mean realizing that your paycheck finally has somewhere to go besides yesterday's problems.
That is why this matters.
You are not simply trying to make a spreadsheet look better. You are trying to create more room in your mind and your life.
Stop letting the next statement decide how you feel about your future. Open your accounts, face the numbers, choose one balance to attack, and make one financial move today. You do not need a perfect plan—you need a first move. Start now, because another year of waiting can cost far more than one uncomfortable afternoon of clarity.
Final Thought: You Are Allowed to Reset
If you have been functioning but not feeling okay, your finances may be part of the reason.
The credit card trap is powerful because it combines mathematics with psychology. Interest keeps balances expensive. Minimum payments make the problem feel manageable. Convenience makes spending easy. Stress makes long-term thinking harder. And shame can keep you from looking closely enough to change anything.
But the cycle is not your identity.
You can interrupt it.
Start with one balance. One statement. One honest number. One spending decision. One payment that moves you forward instead of keeping you in place.
Progress may not feel dramatic at first. That is okay.
Sometimes the biggest financial transformation begins with something almost invisible: the moment you stop avoiding the truth and decide that your money deserves your attention.
That moment can be today.
FAQ — Credit Card Debt
1. Why does credit card debt feel impossible to escape?
Because the balance can grow faster than you expect when high interest, minimum payments, and new purchases work together. You may be paying every month and still feel like nothing is changing. The first breakthrough is knowing exactly what you owe and stopping the cycle of adding new debt.
2. Is paying the minimum payment keeping me trapped in debt?
It can. A minimum payment may keep your account current, but it often does little to reduce the principal quickly. When interest continues accumulating, a balance can take years to eliminate. Paying more than the minimum, whenever your budget allows, can dramatically change the pace of your payoff.
3. How do I get out of credit card debt when I am already overwhelmed?
Do not try to fix everything at once. List your balances, interest rates, and minimum payments first. Then choose one debt to prioritize while making the required payments on the others. Small, consistent wins can create momentum without forcing you into an unrealistic budget.
4. Should I pay off debt or save money first?
For many people, the smartest approach is a combination of both: build a small emergency cushion while aggressively addressing high-interest credit card debt. Without any cash buffer, an unexpected expense can simply push you back onto the credit card.
5. What is the biggest mistake people make when trying to pay off credit cards?
Trying to make an extreme financial change overnight. Cutting everything enjoyable may work temporarily, but an unsustainable budget often leads to burnout and eventually more spending. A realistic system you can maintain month after month is usually more powerful than a perfect plan you abandon after two weeks.
6. Can credit card debt affect my mental health and daily life?
Financial stress can contribute to worry, sleep problems, mental fatigue, and constant preoccupation with money. If you feel like you are functioning on the outside while constantly calculating bills and balances in your head, that stress deserves attention—not shame.
7. What is the fastest way to start breaking the credit card cycle?
Stop making the balance larger, identify your highest-cost debt, and direct every realistic extra dollar toward it. At the same time, create a small cash buffer for unexpected expenses. The goal is to change the direction of your finances, not find a magical overnight solution.
Continue Building Your Financial Clarity
Now that you understand why money anxiety doesn’t go away even when you earn more, the next step is learning how to build a healthier and more peaceful relationship with your money.
You don’t need to fix everything at once.
Start with one small change — one habit, one tool, or one moment of awareness — and observe how your financial mindset begins to shift over time.
You may also like:
👉 The Truth About Money Discipline No One Talks About)
👉 You Don’t Have a Money Problem — You Have a Behavior Pattern
👉 Why You Struggle With Money Even When You Know What To Do
👉 You're Not Bad with Money: You're Repeating Patterns