The Real Reason Your Credit Card Balance Never Seems to Go Down
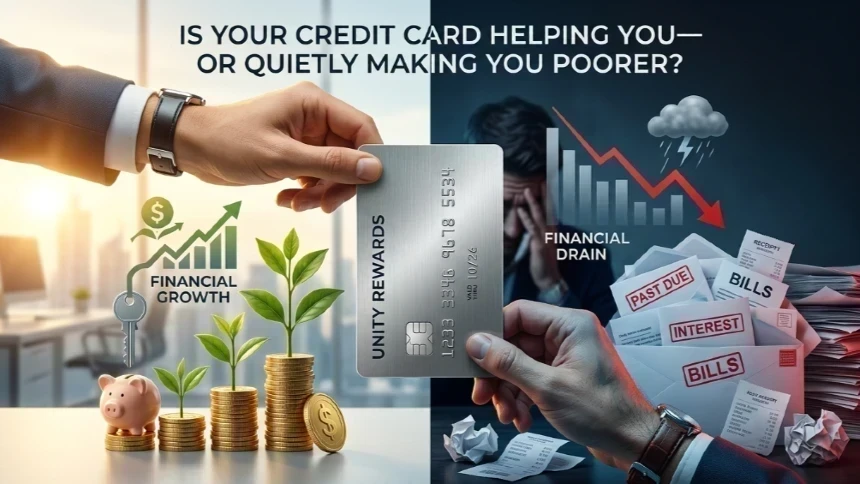
If your credit card balance never seems to go down, even though you make payments every month, there is a good chance you are not failing at money. You may simply be trapped inside a system where interest, minimum payments, new purchases, and mental fatigue work together in ways that are easy to miss.
And honestly, that realization can feel strangely emotional. You open your account, see that you paid $200 or $300 recently, and expect the number to look meaningfully smaller. Instead, it barely moved. Sometimes it is almost exactly where it was before. You start wondering, Where did all that money go?
That question matters because credit card debt is not only a math problem. It can become a mental burden. When you are already juggling work, family responsibilities, notifications, errands, bills, and the invisible emotional labor of keeping everyday life moving, managing another financial problem can feel impossible.
You can be functioning. You can be working. You can be paying your bills. And still quietly feel like something is wrong.
The hidden truth is that your credit card balance may not be going down because your payment is fighting several forces at once. Once you understand those forces, the situation becomes much less mysterious.
Credit Card Balance Problems Usually Start With a Simple Illusion
The first thing to understand is this: making a credit card payment does not automatically mean your debt is shrinking quickly.
Imagine you owe $5,000 and make a $200 payment. It feels significant because $200 is real money leaving your checking account. But your credit card company may add interest during the billing cycle. If you also make $100 of new purchases, the payment is immediately being offset.
In other words, you may be running on a financial treadmill.
You are moving, but you are not getting very far.
This is one reason credit card debt can create such intense emotional exhaustion. You are putting in effort without seeing proportional progress. Eventually, your brain starts protecting itself by avoiding the account altogether.
Minimum payments can create a false sense of progress
Minimum payments are designed to keep your account current, not necessarily to help you eliminate the balance quickly. When you make only the required payment, a significant portion may go toward interest and other charges rather than dramatically reducing the principal.
That does not mean minimum payments are useless. They can help you avoid becoming delinquent when money is tight. But if your goal is to get out of credit card debt, relying on the minimum indefinitely can make the journey much longer.
A simple budgeting tool such as YNAB can also help make the relationship between available cash, upcoming expenses, and debt payments more visible. The value is not in having another app to obsess over. It is in reducing the mental effort required to know what your money is supposed to do next.
Why Interest Makes Your Credit Card Balance Feel Stuck
One of the biggest reasons a credit card balance never seems to go down is interest.
Credit card APRs can be substantially higher than the rates people associate with other types of borrowing. That means carrying a balance can become expensive surprisingly quickly. The longer the balance remains, the more interest can compete with your payments.
This is where many people experience their first major financial wake-up call.
You might think, “I paid $500 toward my card this year, so surely I must be $500 closer to being debt-free.” But the actual reduction in your principal depends on the interest charged and whether you added new purchases along the way.
The number that deserves your attention
Instead of looking only at the minimum payment, look at your APR, current balance, interest charges, and the amount of principal being reduced.
Those numbers tell a much more honest story.
For example, if your statement shows a large interest charge, that is evidence that the balance is costing you money simply by existing. Once you see that clearly, your strategy can change from “How do I make this month's payment?” to “How do I stop this balance from consuming my future cash flow?”
That shift is powerful because it turns a vague financial fear into a specific problem you can solve.
For people who want a clearer picture of how debt payments fit into a larger financial plan, a simple spreadsheet or calculator can be enough. You do not need a complicated financial system. You need visibility.
New Purchases Could Be Canceling Out Your Payments
Here is the uncomfortable part: sometimes your credit card balance is not going down because you are paying it down with one hand and rebuilding it with the other.
This happens constantly in modern life.
You pay $300. Then groceries go on the card. A subscription renews. You order dinner because you are exhausted. You replace something unexpected. A medical or household expense appears. You swipe again.
None of these decisions necessarily look reckless.
That is exactly why the cycle is so difficult to recognize.
When you are mentally exhausted, convenience becomes incredibly valuable. After a long day, the difference between spending $25 on takeout and cooking for another 45 minutes can feel enormous. When your brain is overloaded, immediate relief often wins against an abstract future goal.
This is not necessarily a discipline problem
Financial advice often makes debt sound like a character test. Spend less. Be disciplined. Stop buying things.
Real life is more complicated.
If you are burned out, mentally fatigued, and constantly operating on autopilot, financial decisions can become another source of friction. You may not even notice how frequently small purchases are happening because each transaction feels insignificant in isolation.
A product such as the Rocketbook Smart Reusable Notebook can be useful for people who prefer physically writing down recurring expenses, financial worries, or spending triggers. The point is not the notebook itself. The point is creating a moment where your brain has to slow down and see the pattern.
That pause can be more valuable than another lecture about discipline.
The Emotional Reason You Keep Reaching for the Card
There is another layer that rarely gets discussed: sometimes credit card spending is connected to emotional regulation.
When you feel overwhelmed, buying something can create a tiny feeling of control. When you feel deprived, spending can feel like permission to finally have something for yourself. When you are exhausted, paying for convenience can feel like survival rather than indulgence.
And when the purchase is followed by guilt, the cycle can become even more draining.
Stress leads to spending. Spending leads to anxiety. Anxiety leads to avoidance. Avoidance allows the balance to grow. Then the growing balance creates more stress.
That is not simply a budgeting problem. It is a feedback loop.
Functioning but not okay
You can have a job and still feel financially unsafe.
You can pay every bill and still feel behind.
You can appear responsible to everyone around you while privately avoiding your banking app because you already know the number will make you anxious.
Modern life has normalized this kind of emotional overload. People are expected to work, respond, organize, plan, provide, remember, schedule, save, invest, and somehow remain calm while doing all of it.
So if your financial life feels strangely chaotic, do not automatically assume you need more willpower.
You may need less mental noise.
How to Finally Make Your Credit Card Balance Start Moving
The solution begins with making the situation visible and then creating a repayment system that does not depend on perfect motivation.
Stop adding unnecessary purchases to the balance. Even temporarily reducing new charges can make your payments much more effective.
Write down every credit card balance. Include the balance, APR, minimum payment, and due date.
Choose one repayment priority. You can focus on the highest APR first or use a balance-focused approach that gives you quick psychological wins.
Pay more than the minimum when realistically possible. Even an additional amount can matter when repeated consistently.
Automate what you can. Automation reduces the number of financial decisions you have to remember.
Review recurring charges. Forgotten subscriptions can quietly compete with your debt payments every month.
Give yourself a small buffer. A plan that leaves you completely cash-starved can push you back toward the card when an unexpected expense appears.
The goal is not to create a punishment plan. It is to create a system you can live with.
For example, a person who can consistently pay $450 every month may make more progress than someone who promises to pay $1,000 but cannot sustain it. Consistency matters because debt repayment is not one dramatic decision. It is a series of repeated decisions.
Make progress visible
One surprisingly effective psychological trick is to track your declining balance rather than only your monthly payment.
Seeing $6,200 become $5,850 can feel different from simply seeing another $350 leave your checking account.
You need evidence that your effort is working.
A simple tool like the Apple Health app is not a financial product, but its broader lesson is useful: progress becomes easier to maintain when something is measurable and visible. You can apply the same principle to money by tracking your balance, payment streak, interest charges, and debt reduction over time.
What If You Are Already Overwhelmed?
If reading this makes you want to close the page because your finances already feel like too much, start smaller.
Do not attempt to rebuild your entire financial life tonight.
Open one credit card statement.
Look at four things: your balance, APR, minimum payment, and interest charged.
That is it.
You are not required to solve everything in one sitting.
Once you know those numbers, you have something concrete to work with. Then you can decide whether you need to change your spending, increase your payment, contact your issuer about available options, explore a balance transfer if appropriate, or seek guidance from a qualified nonprofit credit counselor.
Be careful with anyone promising a magical debt solution. If an offer sounds too good to be true, especially if it demands large upfront fees or guarantees a specific result, slow down and investigate before agreeing to anything.
The Reset Is More Important Than the Perfect Budget
The biggest change may not happen when you create the perfect spreadsheet.
It may happen when you stop treating your financial stress as evidence that you are bad with money.
Debt can make intelligent, hardworking people feel ashamed. Shame encourages avoidance, and avoidance makes financial problems harder to see. The healthier approach is curiosity.
Ask: What is actually happening here?
Where is the money going?
How much interest am I paying?
Which purchases are necessary?
Which expenses happen because I am exhausted?
What payment can I realistically maintain?
Those questions are not judgmental. They are diagnostic.
And once you understand the pattern, you can change the pattern.
Your Credit Card Balance Can Change, But the Cycle Has to Change Too
If your credit card balance never seems to go down, the answer is rarely as simple as “try harder.” The real issue may be the combination of high interest, minimum payments, new charges, recurring expenses, and the emotional exhaustion that makes everything harder to manage.
That said, understanding the problem is only the beginning.
Your next step should be small enough to actually happen. Check the statement. Write down the numbers. Identify what keeps getting added. Choose a payment amount. Remove one unnecessary recurring charge. Then repeat the process next month.
You do not need to become a completely different person to get control of your money.
You need a system that works for the person you are right now, even if you are tired, overwhelmed, or starting later than you wanted.
Do not let another month disappear on autopilot. Open your credit card statement today, find the balance and APR, and make one concrete change before you close the app. Your future self does not need perfection from you. She needs you to start breaking the cycle now.
And remember: progress may look painfully small at first. But a balance that is genuinely moving is very different from a balance that only appears to move. The moment you understand what is keeping your debt stuck, you finally have the information needed to change direction.
FAQ — The Real Reason Your Credit Card Balance Never Seems to Go Down
Why does my credit card balance never seem to go down?
Your balance may stay high because interest charges, new purchases, fees, and minimum payments can consume much of what you pay each month. Even consistent payments may produce little progress if new charges continue.
Does paying more than the minimum really help?
Yes. Paying more than the minimum generally allows more of your payment to reduce the principal balance, helping you pay off the debt faster and potentially reducing the total interest you pay.
Why does my balance increase even after I make a payment?
This can happen when new purchases and interest charges are added after or alongside your payment. If the amount you spend plus interest is close to or greater than your payment, the balance may barely change or even increase.
Is credit card debt always a sign that I am bad with money?
No. Credit card debt can result from emergencies, rising living costs, unexpected expenses, high interest rates, or periods of emotional and mental exhaustion. Understanding the pattern is more useful than blaming yourself.
What should I do first if my credit card debt feels overwhelming?
Start with one card. Check the current balance, APR, minimum payment, and recent interest charge. Then identify what continues to be charged to the card. You do not have to solve your entire financial situation in one day.
How can I stop the cycle of paying my credit card and then using it again?
Identify the expenses that are repeatedly going back onto the card and create a plan to cover those expenses with available cash instead. Even temporarily reducing new charges can make your payments much more effective.
Should I pay off the credit card with the highest interest rate first?
The highest-interest-rate approach can save money on interest over time. Another option is focusing on the smallest balance first for quicker psychological wins. The best method is often the one you can consistently follow.
Can financial stress make credit card debt harder to manage?
Absolutely. Mental fatigue and emotional overload can make financial decisions feel exhausting. When you are constantly operating on autopilot, convenience spending and avoidance can become easier, which may keep the debt cycle going.
How quickly can I pay off my credit card balance?
It depends on your balance, APR, minimum payment, and how much you can consistently pay each month. The most important step is to stop the balance from continually being replaced while increasing payments when your budget allows.
Continue Building Your Financial Clarity
Now that you understand why money anxiety doesn’t go away even when you earn more, the next step is learning how to build a healthier and more peaceful relationship with your money.
You don’t need to fix everything at once.
Start with one small change — one habit, one tool, or one moment of awareness — and observe how your financial mindset begins to shift over time.
You may also like:
👉 The Truth About Money Discipline No One Talks About)
👉 You Don’t Have a Money Problem — You Have a Behavior Pattern
👉 Why You Struggle With Money Even When You Know What To Do
👉 You're Not Bad with Money: You're Repeating Patterns