Credit Card Interest Trap: The Part Nobody Explains Clearly
If you have ever made a credit card payment and then opened your account a few weeks later wondering why the balance barely moved, you are not imagining it. The credit card interest trap is real, and it can make responsible people feel as if they are failing at money when the system itself is difficult to understand.
You work. You pay bills. You try to keep everything together. Maybe you even make every payment on time. Yet there is still that uncomfortable feeling that something is off. The balance does not disappear as quickly as you expected. Interest keeps appearing. Another purchase lands on the statement. Suddenly, you are mentally calculating money while trying to fall asleep.
That is where this becomes more than a financial problem. It becomes mental fatigue.
Modern life already asks people to manage work, family responsibilities, schedules, unexpected expenses, digital notifications, and dozens of daily decisions. When credit card debt gets added to that load, it can create a constant background pressure that is easy to normalize. You may be functioning perfectly on the outside while quietly feeling financially exhausted on the inside.
The important truth is this: you do not need to be bad with money to get caught in the credit card interest trap. You need to understand what is happening underneath the minimum payment.
Why the minimum payment feels helpful but can keep you stuck
The minimum payment exists to keep your account current, but it is not designed to make your balance disappear quickly. When you carry a balance, interest can consume part of what you pay before the rest reduces what you owe.
For example, imagine you owe $5,000 on a credit card with a high annual percentage rate. A payment may feel significant when you send it from your checking account, but if interest is accumulating at a substantial rate, the amount actually reducing the balance can be much smaller than you expect.
That creates a psychologically dangerous illusion: you are paying, so it feels like you are making progress. And technically, you may be. But the progress can be painfully slow.
That slow progress is one reason people become discouraged. Discouragement can lead to avoidance. Avoidance can lead to more spending on autopilot. Then the cycle starts again.
For someone trying to regain control, even a simple tool such as a YNAB Budgeting App can provide a clearer picture of where money is going and how much is realistically available for debt payments. The value is not in having another complicated system. It is in making the invisible visible.
How Credit Card Interest Actually Eats Your Payment
The most important thing to understand about the credit card interest trap is that your payment and your balance are not the same thing. When interest is added, your account can grow even while you are making payments.
Your credit card issuer generally calculates interest based on your balance and the card's annual percentage rate, often using a daily periodic rate. The exact calculation depends on the card agreement, but the basic idea is simple: carrying a balance has a cost, and that cost continues to accumulate.
A simple example
Suppose you have a $4,000 balance at a 24% APR. A rough monthly interest estimate would be about 2% of the balance, or approximately $80, although actual credit card interest calculations can differ.
Now imagine you make a $150 payment. It feels like you just removed $150 of debt. But if around $80 represents interest for that period, only about $70 is left to reduce the balance before considering any new purchases or other charges.
Suddenly, the situation looks completely different.
This is why a person can spend months making payments and still feel like the finish line keeps moving. The problem is not necessarily that the person is not trying hard enough. The problem is that interest is quietly working in the opposite direction.
Why high APR matters so much
A credit card with a high APR can make debt repayment significantly more expensive. Two people might owe the same amount, make similar payments, and still experience very different results because their interest rates are different.
This is one reason the APR deserves your attention before rewards, points, welcome bonuses, or flashy card benefits. A rewards card may look attractive when you are focused on what you receive from purchases. But if you regularly carry a balance, interest can overwhelm the value of those rewards.
In other words, earning a few dollars in rewards while paying substantial interest is rarely the financial victory it appears to be.
A basic financial calculator, spreadsheet, or even a simple notebook can help you compare your balance, APR, monthly interest, and payment amount. You do not need a perfect financial system. You need clarity.
The Emotional Side of Credit Card Debt Is Bigger Than People Admit
Money stress rarely stays inside your bank account. It follows you into your morning routine, your conversations, your shopping decisions, and sometimes your sleep.
You may find yourself checking your balance repeatedly. You may avoid opening statements. You may feel guilty buying something small, even when you can technically afford it. Or you may reach a point where you are so mentally exhausted that you stop looking altogether.
That last stage can be especially dangerous because financial avoidance feels like relief in the short term.
You do not have to think about the balance for a few hours. You get a break from the numbers. But the interest does not take a break.
This is why financial burnout deserves to be discussed alongside budgeting. A person experiencing mental overload may know exactly what they should do and still struggle to do it consistently. That does not automatically mean they lack discipline.
Functioning does not always mean you are okay
Maybe you are paying your bills. Maybe you are working full-time. Maybe everyone around you thinks you have everything under control.
And yet, every unexpected expense feels like a small emergency.
Every credit card notification creates tension.
Every payday feels less like progress and more like another opportunity to catch up.
This is the hidden emotional cost of revolving debt. It can make normal life feel financially fragile.
A simple comfort-focused routine can sometimes make the process easier to sustain. Something as ordinary as a Thermos Stainless King Travel Tumbler can become part of a morning reset that gives you ten quiet minutes to review your finances without turning the entire day into a money crisis. The product itself does not solve debt. The point is creating a small, repeatable ritual around a difficult task.
When financial management becomes less emotionally overwhelming, you are more likely to keep doing it.
Why Small Purchases Can Keep the Credit Card Interest Trap Alive
Here is another uncomfortable truth: sometimes the problem is not one enormous purchase. It is the accumulation of dozens of tiny decisions made while tired, stressed, busy, or emotionally drained.
A coffee here. Delivery there. A subscription you forgot about. A convenient purchase because you had no energy to compare prices. A few online orders after a difficult day.
None of these decisions necessarily looks disastrous by itself.
But when those purchases land on a revolving credit card balance, they can become more expensive than their sticker price suggests because interest may continue accumulating on the balance.
The exhaustion spending cycle
You feel mentally overloaded.
You make a convenient purchase because it reduces friction.
The purchase goes on the credit card.
Your balance increases.
Interest increases the cost of carrying that balance.
You feel more financial pressure.
The pressure makes future decisions harder.
That cycle can continue quietly for months.
The answer is not to eliminate every enjoyable purchase or live in constant restriction. Extreme rules often fail because they create emotional rebound. Instead, create a small amount of intentional spending that you can actually maintain.
For example, decide in advance how much discretionary money you can use each week. When that amount is gone, pause. This creates a boundary without requiring you to make a complicated decision every time you feel stressed.
A simple Rocket Money account review can also help identify recurring subscriptions and forgotten expenses that are quietly consuming cash flow. The goal is not to obsess over every dollar. It is to remove financial noise so your money has a clearer direction.
How to Break the Credit Card Interest Trap Without Trying to Fix Everything at Once
If you are overwhelmed, do not start by trying to rebuild your entire financial life in one weekend. That sounds productive, but it often creates another burst of motivation followed by exhaustion.
Instead, focus on the few actions that can create the biggest change.
1. Stop adding unnecessary debt
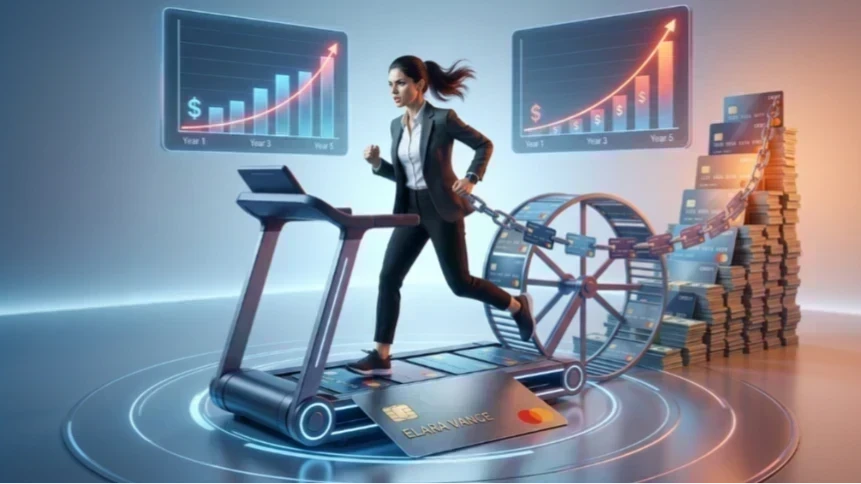
Before you worry about perfect repayment strategies, look at whether the balance is still increasing. If you continue charging more than you can comfortably pay off, even an aggressive repayment plan can feel like running on a treadmill.
Identify the purchases that can temporarily move to cash or debit. This is not about punishment. It is about stopping the leak before filling the bucket.
2. Write down every credit card balance
Put the numbers somewhere visible and simple. Record the balance, APR, minimum payment, and due date for each card.
Seeing the complete picture may feel uncomfortable at first. That discomfort is useful. Uncertainty often creates more anxiety than facts do.
3. Keep every account current
Missing payments can create additional financial consequences, including late fees and potential damage to your credit history. Make minimum payments on time while directing any extra money toward your chosen priority.
4. Choose a repayment strategy
Two common approaches are the debt avalanche and debt snowball methods.
The avalanche method prioritizes the debt with the highest interest rate, which can reduce interest costs over time. The snowball method focuses on the smallest balance first, creating quick psychological wins that may help maintain motivation.
Neither method is magically perfect for everyone. The best strategy is the one you can follow consistently.
5. Look for ways to lower interest
Depending on your situation and eligibility, options may include a lower-interest balance transfer, a personal loan used for consolidation, or contacting your issuer to ask about available hardship or repayment options.
Read the terms carefully before moving debt. A lower introductory rate can be useful, but balance transfer fees, expiration dates, and other conditions matter.
6. Create a tiny financial reset ritual
Choose one day each week for a 15-minute money check-in. Review your balance, recent spending, upcoming bills, and debt payment progress.
Then stop.
You do not need to spend the entire evening thinking about money. The purpose is to contain the stress instead of allowing it to follow you all week.
What Happens When You Finally Understand the Numbers
There is a moment that often changes everything: the moment your credit card balance stops feeling like a mysterious force and starts looking like a problem with specific numbers.
You know the balance.
You know the APR.
You know approximately how much interest is being charged.
You know how much you can realistically pay.
You know which balance you are targeting first.
That clarity matters because fear thrives in uncertainty.
Once you can see the moving parts, you can make decisions instead of reacting to surprises.
And this is where the emotional shift begins. You may still have debt. You may still have months of repayment ahead. But you are no longer operating completely on autopilot.
That distinction is powerful.
The Goal Is Not Perfect Money Management
One of the biggest mistakes people make after realizing they have a credit card problem is swinging to the opposite extreme. Suddenly, every purchase feels wrong. Every dollar must be optimized. Every financial mistake becomes evidence that they are failing.
That mindset is exhausting, and exhaustion rarely creates sustainable financial behavior.
The real goal is not perfection. It is awareness.
You want to reach the point where your credit card is a tool rather than a source of constant anxiety. You want purchases to be intentional. You want your balance to move in the direction you expect. Most importantly, you want money to occupy less mental space.
Because financial freedom is not only about having more money.
It is also about having fewer financial emergencies competing for your attention.
A healthier way to think about progress
One less unnecessary charge is progress.
One extra payment is progress.
One avoided late fee is progress.
One honest look at your balance is progress.
One week of intentional spending is progress.
One month without adding new revolving debt is progress.
These actions may look small, but small decisions repeated consistently can change the direction of your finances.
Your Credit Card Balance Is a Problem to Solve, Not a Judgment of Your Worth
If you have been carrying credit card debt while feeling mentally exhausted, remember this: the balance is a financial number, not a measurement of your intelligence, discipline, or value.
Maybe you made mistakes. Most people do.
Maybe an emergency pushed you into debt. Maybe rising costs made your budget impossible. Maybe you were simply trying to get through a difficult season.
Whatever happened, shame will not reduce the balance. Clarity can.
The credit card interest trap becomes less powerful when you understand exactly how it works and stop allowing minimum payments, automatic spending, and emotional avoidance to make every decision for you.
You do not need to solve your entire financial future today. You need to make the next clear decision.
Open your credit card statements today. Write down every balance, every APR, and every minimum payment. Then choose one debt to attack first. Do not wait until you feel financially confident. Clarity comes from action, and the fastest way to weaken the interest trap is to stop looking away from it.
Start small. Stay consistent. Give your future self fewer things to worry about.
Because the moment you understand where your money is going, you can finally start deciding where it should go.
FAQ — The Credit Card Interest Trap
1. Why does my credit card balance keep growing even when I make payments?
Because making a payment does not necessarily eliminate the interest accumulating on your balance. When you carry debt from one billing cycle to another, interest can take a significant portion of your payment before the remaining amount reduces the principal. If you continue making new purchases, your balance can stay high or even increase.
2. Is paying only the minimum payment a bad idea?
Paying the minimum can keep your account current, but it can take much longer to eliminate the debt and may result in paying substantially more interest over time. If you can afford to pay more than the minimum, directing extra money toward your credit card balance can help you escape the debt faster.
3. What is the fastest way to get out of the credit card interest trap?
Start by stopping unnecessary new charges, then list every credit card balance, APR, and minimum payment. Keep all accounts current and direct extra money toward the card with the highest interest rate if your priority is reducing interest costs. The key is consistency rather than trying to make one enormous payment and then abandoning the plan.
4. Why does credit card debt feel impossible to pay off?
High interest, minimum payments, new purchases, and emotional exhaustion can combine into a cycle that makes progress feel invisible. You may be making payments every month while the balance decreases much more slowly than expected. Understanding the numbers can turn that feeling of helplessness into a concrete repayment plan.
5. Should I stop using my credit cards completely?
Not necessarily. The important question is whether you can use the card without increasing a balance you cannot pay off. If you are already carrying significant revolving debt, temporarily reducing or stopping new charges may make it easier to regain control and focus on repayment.
6. Is a balance transfer worth considering?
It can be, depending on the terms and your ability to avoid adding new debt. A balance transfer may offer a lower introductory APR, potentially reducing interest costs for a period of time. However, transfer fees, the length of the promotional period, and the interest rate after the promotion ends all matter.
7. What should I do if credit card debt is causing constant financial anxiety?
Start with one short financial check-in instead of trying to fix everything at once. Write down your balances, interest rates, minimum payments, and available monthly payment amount. Turning an unclear problem into specific numbers can reduce uncertainty and help you decide what to tackle first.
8. Can small purchases really make credit card debt worse?
Yes. Small purchases may seem harmless individually, but repeated spending can keep a revolving balance high. When those purchases are carried from month to month, interest can increase their effective cost. The problem is often not one dramatic purchase but dozens of automatic decisions made while stressed, busy, or mentally exhausted.
9. How long will it take to pay off my credit card?
It depends on your balance, APR, and payment amount. A higher payment generally reduces the balance faster and limits the amount of interest that accumulates. The most useful first step is to calculate your repayment timeline using your actual numbers rather than relying on how quickly you hope the debt will disappear.
10. Can I escape the credit card interest trap even if I feel financially overwhelmed?
Yes. You do not have to solve your entire financial situation overnight. Start with one balance, one payment strategy, and one weekly money check-in. Financial progress becomes much easier when you replace avoidance with small, repeatable actions.
Continue Building Your Financial Clarity
Now that you understand why money anxiety doesn’t go away even when you earn more, the next step is learning how to build a healthier and more peaceful relationship with your money.
You don’t need to fix everything at once.
Start with one small change — one habit, one tool, or one moment of awareness — and observe how your financial mindset begins to shift over time.
You may also like:
👉 The Truth About Money Discipline No One Talks About)
👉 You Don’t Have a Money Problem — You Have a Behavior Pattern
👉 Why You Struggle With Money Even When You Know What To Do
👉 You're Not Bad with Money: You're Repeating Patterns