Financial mistakes when money gets tight often start before you even notice
Financial mistakes when money gets tight rarely begin with one reckless purchase. More often, they begin with exhaustion. You are tired, overwhelmed, checking your bank account less often, hoping the situation will somehow feel better tomorrow. Bills keep coming, groceries cost more than expected, and suddenly every small decision feels heavier than it should.
That is the hidden part nobody talks about enough: when money becomes stressful, your brain does not always become more logical. Sometimes it goes into survival mode.
You may start avoiding your banking app. You may postpone opening an email. You may spend money on something small because you desperately need one moment of comfort. Then, later, you feel guilty and wonder why you keep making choices that seem to make everything harder.
If this sounds familiar, you are not irresponsible. You may simply be mentally overloaded.
Modern life has normalized functioning while quietly falling apart. Many people, especially women balancing work, family responsibilities, emotional labor, and endless decisions, continue showing up every day while carrying financial stress in the background. They look fine. They work. They answer messages. They make dinner. But internally, something feels off.
And when money gets tight, that invisible exhaustion can turn into expensive financial decisions.
The first mistake: making decisions from panic instead of clarity
When your financial situation feels uncertain, panic creates urgency. Everything suddenly feels like an emergency.
You might rush to transfer money, borrow from someone, use a credit card without checking the interest rate, cancel something important, or sell an asset simply because you want the uncomfortable feeling to disappear.
The problem is not that urgency is always wrong. Sometimes financial situations genuinely require immediate action. The problem is confusing emotional urgency with actual urgency.
Before making a major money decision, pause and ask yourself: What exactly is happening right now?
How much money do I actually have available?
Which bills are truly urgent?
What expenses are essential this week?
What can wait?
What am I assuming without checking?
Those questions may sound simple, but clarity is powerful when your nervous system is overloaded. Facts interrupt catastrophic thinking.
A simple notebook can help, but many people find it easier to separate emotional thoughts from financial facts using something like the Rocketbook Core Smart Notebook. Writing everything down can create distance between the feeling of being overwhelmed and the actual numbers in front of you.
In other words, do not make your next financial move just to escape discomfort. Make it because you understand what the situation requires.
The second mistake: avoiding your financial reality
Avoidance feels protective in the short term. Unfortunately, it often makes money problems feel larger than they actually are.
When you stop checking balances, ignore bills, avoid statements, or refuse to calculate what you owe, your imagination takes control. The unknown becomes terrifying.
This is one of the most common financial mistakes when money gets tight because avoidance temporarily reduces anxiety. You do not have to think about the number if you do not look at it.
But the bill still exists.
The subscription still renews.
The payment date still arrives.
And as a result, the situation can quietly become more complicated.
Truth moment: knowing is usually less painful than wondering
There is a strange relief that happens when you finally look at the numbers. You may not like what you see, but uncertainty begins to shrink.
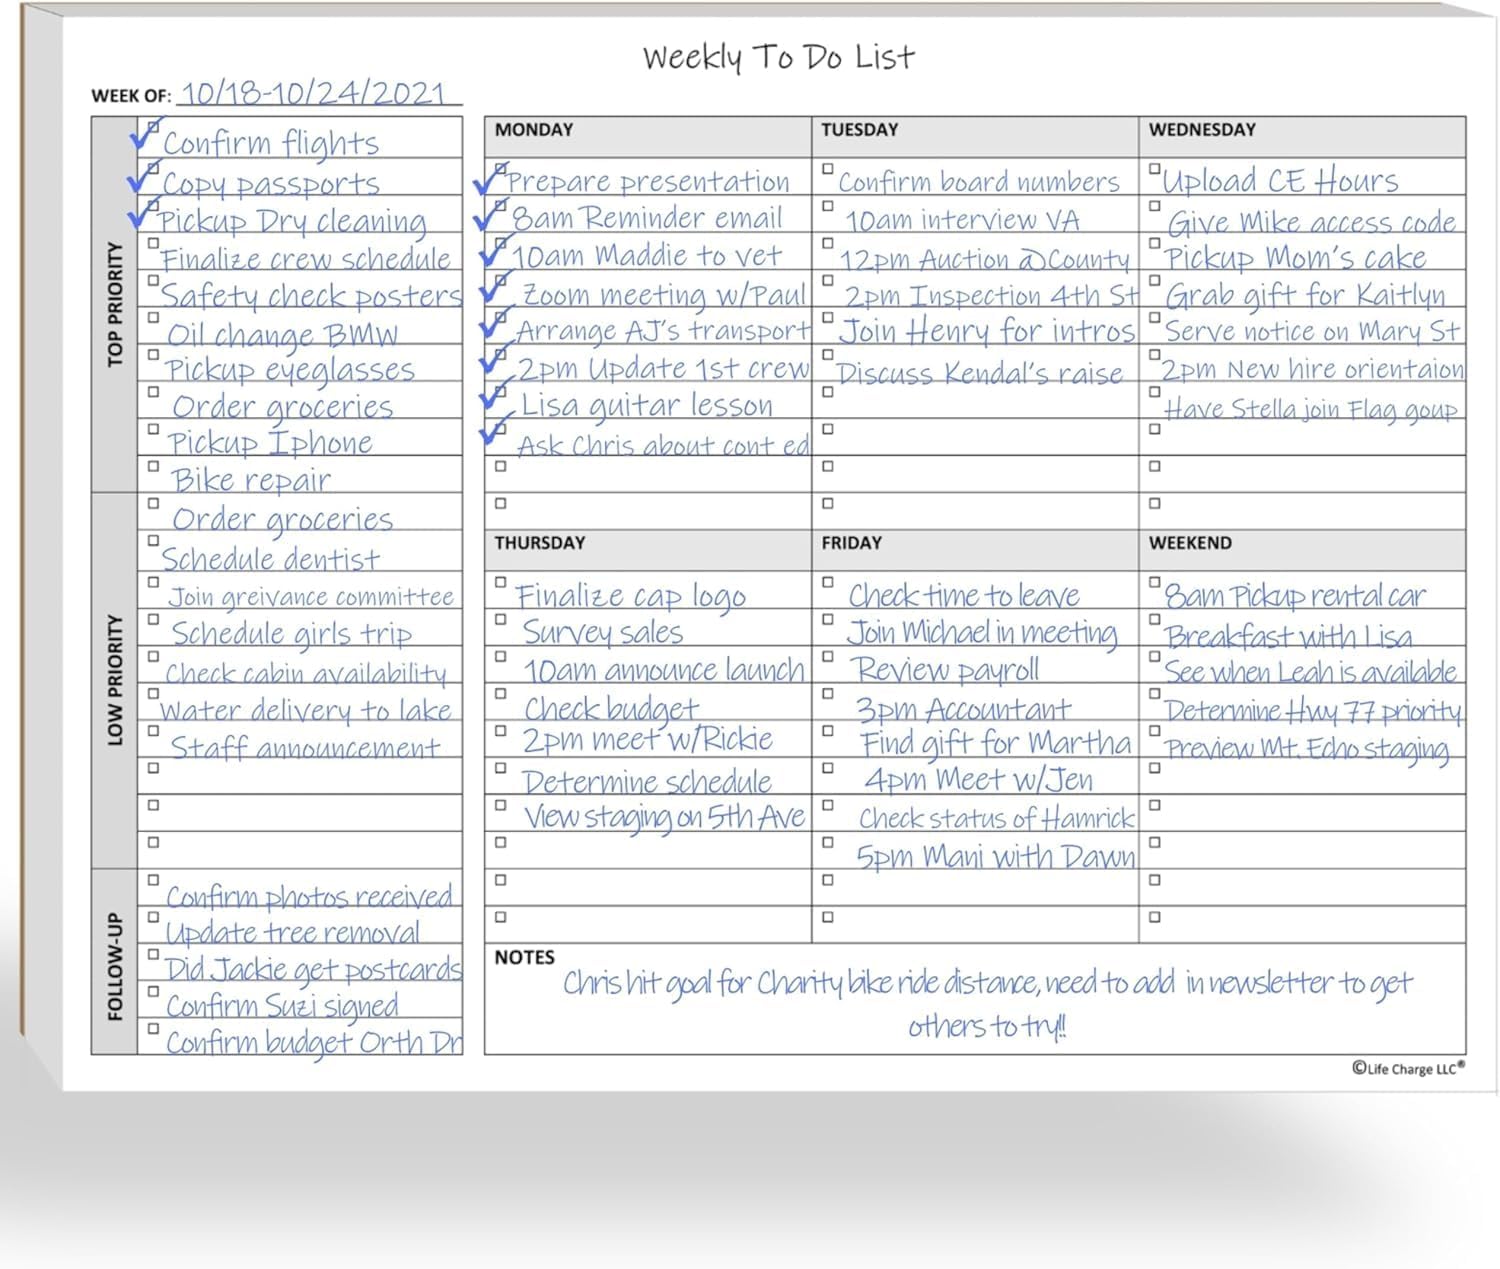
Try creating one short financial snapshot:
Write down your current available cash.
List every bill due in the next 30 days.
Mark essential expenses first.
Identify minimum debt payments.
Remove assumptions and use real numbers.
This is not about creating the perfect budget. It is about ending the mental fog.
If budgeting spreadsheets make you feel like you need another degree, a simple app such as YNAB can help some people organize spending around actual priorities instead of guessing where their money went. The goal is not perfection. The goal is visibility.
Once you can see the situation, you can start making decisions. Until then, fear tends to make decisions for you.
The third mistake: cutting everything until life feels unbearable
When money gets tight, people often swing from one extreme to another.
Yesterday, spending felt uncontrolled. Today, they decide they will spend absolutely nothing.
No coffee. No entertainment. No small comforts. No flexibility. No exceptions.
At first, extreme restriction can feel empowering. You finally feel disciplined. You are taking control.
However, there is a reason this approach often collapses.
Humans are not spreadsheets.
If your financial plan ignores stress, fatigue, family needs, and emotional reality, it may work for a few days and then explode into rebound spending. You become so exhausted from saying no to everything that one difficult day turns into an impulsive shopping spree, expensive takeout, or another purchase you promised yourself you would not make.
Instead, reduce pressure strategically
Look for temporary adjustments rather than punishment.
Pause subscriptions you barely use.
Reduce convenience spending for a specific period.
Plan lower-cost meals without making food miserable.
Delay nonessential purchases instead of permanently banning them.
Create a small amount of guilt-free spending if your budget allows it.
The healthiest financial reset is often the one you can actually repeat.
This matters because financial stress is already emotionally draining. If your money plan makes your life feel even more impossible, your brain will eventually resist it.
The fourth mistake: using credit to hide the problem
Credit cards can be useful financial tools. The danger appears when credit becomes a way to avoid acknowledging that your income and expenses are no longer matching.
When money gets tight, it can be tempting to tell yourself that next month will be different. So you put groceries, bills, or everyday purchases on a card and hope future income will solve today's gap.
Sometimes that decision is necessary. Emergencies happen. Life is unpredictable.
But repeated borrowing without a plan can quietly turn temporary pressure into long-term financial stress.
The important question is not simply, Can I put this on my credit card?
Ask instead, What is the realistic plan for paying this back?
If the answer is unclear, pause before adding more debt.
This is also a good moment to review your full financial picture rather than focusing on one transaction at a time. A simple digital planning system like the Notion Budget Planner can help organize bills, debt, goals, and monthly spending in one place for people who prefer seeing everything together.
The purpose is not to become obsessed with tracking every dollar. It is to stop allowing hidden decisions to accumulate in the background.
The fifth mistake: trying to solve everything at once
Financial stress creates a powerful urge to fix your entire life immediately.
You decide you need to pay off all debt, build an emergency fund, increase your income, cancel subscriptions, start investing, meal prep, sell unused items, and become a completely different person by Monday.
That level of pressure is exhausting before you even begin.
Moreover, trying to solve everything at once can make you feel like a failure when you inevitably cannot do everything.
Instead, identify the most important financial problem in front of you.
Choose the next right move
Your priority might be:
Preventing an overdraft.
Covering rent or housing.
Paying a minimum debt obligation.
Reducing one recurring expense.
Creating a one-week spending plan.
Finding a small amount of additional income.
One clear action can restore more confidence than twenty ambitious intentions.
Financial progress often looks boring from the outside. Nobody applauds you for opening your bank account, canceling one unused subscription, or planning groceries before shopping.
Yet those small actions create something incredibly valuable: evidence that you are no longer completely powerless.
The sixth mistake: making comfort spending your only form of relief
Money is emotional, even when we pretend it is purely mathematical.
After a stressful day, spending can feel like relief. A package arriving at your door can create anticipation. Ordering food can remove one decision. Buying something new can briefly make life feel more interesting.
None of this makes you weak.
The problem appears when spending becomes your primary way to regulate stress.
If you are emotionally exhausted, your brain naturally looks for fast rewards. Unfortunately, those rewards can become expensive when repeated automatically.
That is why financial wellness cannot be separated entirely from emotional wellness.
Ask yourself what else helps you decompress. A walk. A shower. Music. Journaling. Calling someone. Going to bed earlier. Reading. Quiet time without notifications.
These alternatives may sound almost too simple, but mental fatigue changes financial behavior. When your mind has no recovery time, every decision becomes harder.
For many overwhelmed people, creating a small evening reset can be surprisingly effective. The point is not to become perfectly productive. It is to stop reaching for your wallet every time your nervous system asks for relief.
The seventh mistake: believing a difficult season means you failed
This may be the most emotionally damaging mistake of all.
You experience one difficult month and immediately create a story about yourself.
I should be better at this.
Everyone else seems fine.
I make money, so why am I struggling?
I will never get ahead.
But financial difficulty is not always proof of personal failure. Sometimes expenses rise. Sometimes income changes. Sometimes life becomes expensive in ways you could not predict.
And sometimes you have simply been carrying too much for too long.
Silent burnout can affect everything, including money. When you are functioning but not okay, financial decisions become another item on an already overloaded mental checklist.
The answer is not shame.
The answer is awareness.
How to reset when money feels overwhelming
You do not need a dramatic transformation tonight. You need a moment of honesty and a simple next step.
Look at the numbers. Replace assumptions with facts.
Protect essentials. Focus on housing, food, transportation, utilities, and critical obligations.
Pause emotional decisions. Give yourself time before borrowing, canceling, or making major purchases.
Reduce one source of financial pressure. Find one bill, subscription, or expense you can adjust.
Create a short-term plan. Focus on the next seven to thirty days.
Stop demanding perfection. A realistic plan is more valuable than an impressive plan you abandon.
That said, clarity does not mean every financial problem disappears immediately. It means you stop adding unnecessary chaos to an already stressful situation.
If you need more help building a calmer money routine, explore our related guides on financial awareness, personal finance habits, and practical strategies for money and emotional stress. Sometimes the breakthrough is not earning more overnight. Sometimes it is finally understanding the patterns that keep draining your energy and your bank account.
The quiet shift that changes everything
The most important thing to remember is this: money problems become harder when you fight them while exhausted, ashamed, and disconnected from reality.
You do not need to become a different person to regain control.
You need to slow down enough to see what is actually happening.
That is the shift.
Not panic.
Not punishment.
Not pretending everything is fine.
Clarity.
When money gets tight, your instinct may be to rush. But sometimes the smartest financial decision is to stop for ten minutes, breathe, look at the numbers, and refuse to let fear make every decision for you.
Do not wait until financial stress becomes your normal. Open your bank account, face the numbers, choose one problem you can solve today, and take action before another month disappears on autopilot. Your financial reset does not require perfection. It requires one honest decision—and the courage to make the next one.
Money gets tight. Life gets overwhelming. Unexpected expenses happen. But you are not required to respond by shutting down.
You can look. You can adjust. You can begin again.
And sometimes, that quiet decision to face reality is where real financial progress finally starts.
For your next step, read our guides on financial tools and resources and discover more practical ways to build a life where money creates more stability instead of more mental noise.
Frequently Asked Questions
What should I do first when money suddenly gets tight?
Start by facing the numbers instead of reacting to fear. Check your available cash, upcoming bills, minimum debt payments, and essential expenses. The fastest way to regain control is not to panic or cut everything—it is to understand exactly where you stand.
Why do I make worse financial decisions when I am stressed?
Financial stress creates mental fatigue and survival-mode thinking. When your brain is overloaded, you are more likely to avoid bills, overspend for emotional relief, borrow without a plan, or make rushed decisions. The problem is often not a lack of discipline—it is decision fatigue combined with financial pressure.
Should I use my credit card when I don't have enough money?
A credit card can provide temporary flexibility, especially during a genuine emergency. However, using credit without a realistic repayment plan can turn a short-term cash problem into long-term debt. Before charging an expense, ask yourself when and how the balance will realistically be paid.
Is cutting all unnecessary spending the best solution?
Not always. Extreme restrictions can create frustration, burnout, and rebound spending. A better strategy is to temporarily reduce the expenses that matter least while protecting the routines and small comforts that help you maintain a realistic financial plan.
How can I stop feeling overwhelmed by my finances?
Stop trying to solve your entire financial life at once. Focus on one clear priority, such as covering an essential bill, reducing one recurring expense, or creating a spending plan for the next seven days. Small actions create momentum, and momentum reduces financial anxiety.
What is the biggest financial mistake people make during hard times?
The biggest mistake is allowing fear to make every decision. Avoiding accounts, ignoring bills, borrowing impulsively, and spending emotionally can make a difficult situation worse. Clarity may feel uncomfortable at first, but knowing the truth about your finances gives you the power to make smarter decisions.
Can financial stress affect emotional health and decision-making?
Yes. Constant money pressure can contribute to mental exhaustion, poor sleep, anxiety, and decision fatigue. When someone is functioning but emotionally overwhelmed, even simple financial choices can feel impossible. Creating mental space and simplifying decisions can be an important part of regaining financial control.
Continue Building Your Financial Clarity
Now that you understand why money anxiety doesn’t go away even when you earn more, the next step is learning how to build a healthier and more peaceful relationship with your money.
You don’t need to fix everything at once.
Start with one small change — one habit, one tool, or one moment of awareness — and observe how your financial mindset begins to shift over time.
You may also like:
👉 The Truth About Money Discipline No One Talks About)
👉 You Don’t Have a Money Problem — You Have a Behavior Pattern
👉 Why You Struggle With Money Even When You Know What To Do
👉 You're Not Bad with Money: You're Repeating Patterns